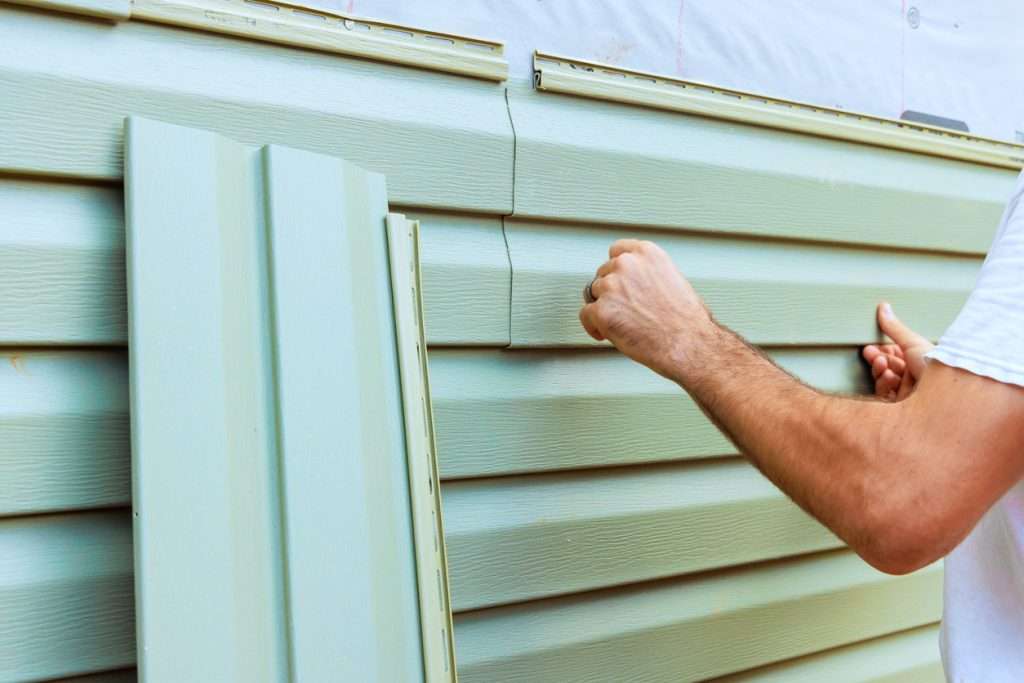
Siding takes the third-biggest storm hit after roofs and gutters. When a bad system rolls through Bergen County — a summer squall, a coastal remnant tracking north, a nor’easter tail — siding catches wind-torn shingles, windborne debris, hail impact, and torn tree limbs. Panels crack. Sections tear away. Impact marks leave hidden entry points for water. And unlike roof or gutter damage that’s obvious from the driveway, siding damage often shows up weeks later as water damage inside wall assemblies — mold in the drywall, warped insulation, foundation problems that trace back to a single unresolved storm.
Here’s the real homeowner’s action guide for the first 48 hours after siding storm damage across Bergen County — Hackensack, Paramus, Fair Lawn, Ridgewood, Teaneck, Fort Lee, Englewood, Bergenfield, and every town in between. From a licensed local general contractor that handles siding, roofing, and gutter storm response across Bergen.
This post completes the Bergen County storm response trilogy alongside our guides on roof storm damage in the first 48 hours and gutter storm damage in the first 48 hours. Bad storms rarely damage only one system. If yours hit multiple, work through all three.
Safety First — Before You Inspect
- Watch for damaged panels ready to fall. Wind-loosened siding can drop suddenly. Don’t stand directly under compromised sections.
- Assume any exposed sheathing is a water entry point. Even if it looks dry now, the next rain can dump water into the wall assembly.
- Downed power lines near the property. Metal siding can conduct current from downed lines. Stay clear until utility company clears the area.
- Watch for hidden interior water damage. Moisture on interior walls, mold spots, damp insulation — these can precede structural problems in the wall assembly.
- Broken glass around the property. Storm-impacted siding often means broken windows and doors nearby. Watch where you step.
Hours 0–4: The Ground-Level Siding Inspection
Once it’s safe to be outside, walk the property perimeter and document everything visible from the ground.
- Check each wall face from the ground. Wind-torn panels show as gaps, misalignment, or displaced sections. Missing panels expose the sheathing underneath.
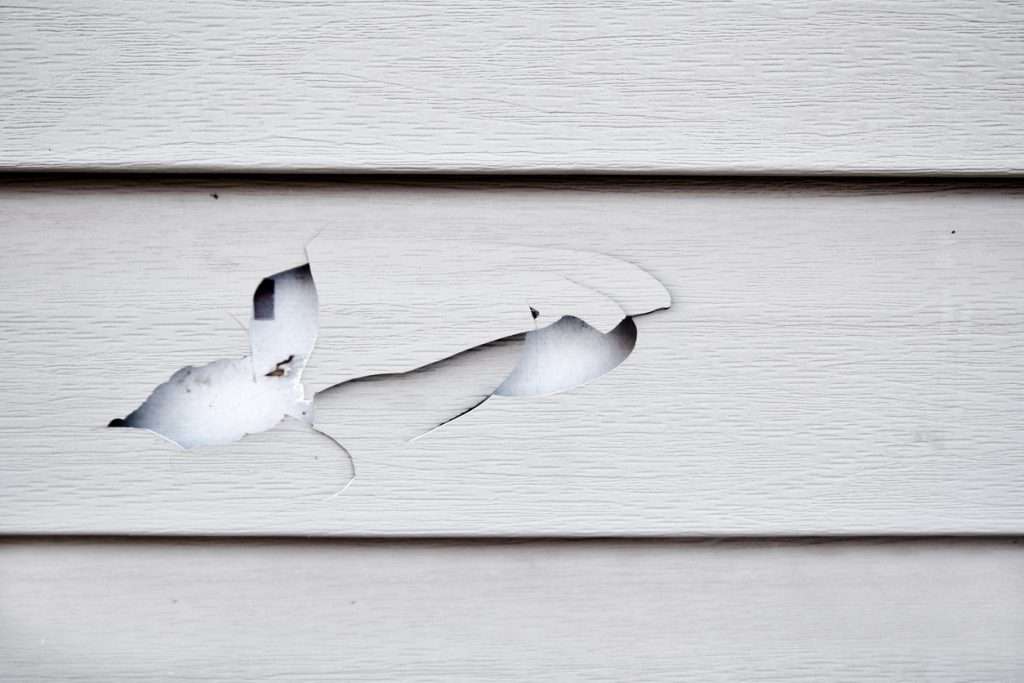
- Look for impact damage. Hail dents, holes from windborne debris, tree-limb impact marks. Some impact damage is barely visible from ground — bring binoculars if you have them.
- Check the corners and around windows/doors. These transition points are the most vulnerable during high wind. Damaged trim or lifted panels around openings are a common storm pattern.
- Inspect the foundation/base of walls. Displaced ground-level siding, damaged foundation flashing, or soil kicked up against the siding.
- Photograph everything. Wide shots of each side of the house. Close-ups of visible damage. Damaged siding pieces on the ground count as evidence.
- Check inside the house too. Water on interior walls, damp insulation visible in outlets, musty smells in rooms adjacent to storm-damaged exterior walls — all early signs of water intrusion.
- Note the color and material of your siding. Vinyl, fiber cement, wood, aluminum, stucco — different materials fail differently in storms. Matching replacement materials matters for the insurance claim and the aesthetic outcome.
Hours 4–12: Insurance Notification
Report the loss to your homeowner’s insurance company right after documentation is complete.
- Have your policy number ready.
- Report the date and time of the storm. The NOAA New York area weather forecast office covers Bergen County and maintains storm records supporting siding claims.
- Describe the siding damage specifically. Wind-torn panels, hail impact, missing sections, damaged trim. Note if roof or gutters also took damage — most policies handle bundled exterior damage as a single event.
- Ask about your deductible. Some policies apply separate wind/hail deductibles differently than the general homeowner deductible.
- Ask about matching provisions. Older siding may be discontinued or hard to color-match. Some policies require exact match; others allow reasonable substitute. This affects your claim.
- Get a claim number. Every subsequent communication references it.
- Ask about temporary protection allowances. Insurance often reimburses temporary tarping to prevent secondary water damage.
Damaged siding causes hidden interior damage fast. Water intrusion into wall assemblies can cause mold, insulation failure, and structural damage within days of the storm — none of which is visible from the outside.
Hours 12–24: Temporary Protection
If your siding has openings that expose sheathing to weather, temporary protection prevents secondary damage until permanent repair. This is a professional job.
- Temporary tarping over damaged sections. Weather-sealed cover to keep water out of wall assemblies until permanent siding can be installed.
- Plywood covers for large exposed sections. More secure than tarps for larger openings, holds up through multiple rain events.
- Sealing around damaged windows and doors. Damaged flashing or trim around openings needs immediate weatherproofing.
- Do NOT accept storm-chaser “quick fix” quotes. Same storm-chaser dynamic hits siding contractors as roofing and gutter contractors. Many out-of-state operations offer fast, cheap repairs that fail within months.
- Verify the licensed local contractor before signing anything. New Jersey HIC registration, real business address, real insurance, real Bergen-area references.
Our post on when siding needs replacement covers the underlying scope for permanent siding work — worth reading before hiring anyone for the permanent repair.
Hours 24–48: Get Real Estimates
- Get 2–3 estimates from licensed local contractors. Not the guy who knocked on your door offering a quick fix.
- Get roofing, gutters, and siding estimated together if all three are damaged. A single contractor handling all three is easier to coordinate with insurance and easier to warranty. See our companion posts on roof storm damage and gutter storm damage.
- Verify the NJ home improvement contractor (HIC) license.
- Verify insurance. Real general liability, workers’ comp, and siding-installation-specific coverage. Request a certificate of insurance with your name as certificate holder.
- Verify local addresses and phone numbers. Storm-chasing operations often list out-of-state addresses or virtual numbers.
- Get the estimate in writing. Scope of work, materials, matching provisions, timeline, warranty, price.
- Ask about matching materials. Newer siding types may be readily available; older or discontinued profiles require sourcing or partial replacement decisions.
- Do NOT sign an Assignment of Benefits. Transfers your insurance claim rights to the contractor. Red flag for legitimate NJ contractors.
The Matching Problem
Siding storm claims often turn on the matching problem. If a storm damaged only one side of your home, your insurance might approve replacing only that side. But if the color or profile can’t be exactly matched (discontinued lines, weathered original panels no longer available in original color), your home ends up with mismatched siding — one wall in a slightly different color than the other three.
- Ask about matching provisions in your policy. Some policies mandate exact matching (paying to replace all four sides to maintain uniformity). Others don’t.
- Document the exact siding profile and color. Manufacturer, product line, color code if available. Older siding may not have this documentation available.
- Discuss aesthetic outcome upfront. If you’re going to end up with visibly different siding on different walls, know it before the work starts.
Bundling with Roof and Gutter Repair
Big storms almost never damage siding alone. If your siding took damage, the roof and gutters likely took damage from the same event.
- Roof damage above the siding. Torn shingles, damaged flashing, or gutter overflow — all can create secondary siding damage.
- Gutter damage adjacent to siding. Water no longer routing correctly hits siding and causes secondary damage.
- Trim, flashing, and transition points. Damaged transition points between roof, gutter, and siding are where many secondary water intrusion problems start.
- One contractor, one warranty, one insurance conversation. Bundling roofing, gutter, and siding damage into one project has real advantages.
The Bergen County Storm-Chaser Warning
Storm-chaser contractors work siding as aggressively as roofing. Same red flags apply:
- Door-knocking within 24 hours is a red flag.
- Free inspection offers with immediate sales pitches are a red flag.
- Out-of-state license plates, addresses, phone numbers are red flags.
- Pressure to sign immediately is a red flag.
- Full payment up front is a red flag.
- Assignment of Benefits paperwork is a red flag.
- “We can match your existing siding no problem” claims without inspecting the profile are a red flag.
Bergen County residents can verify contractor credentials through the NJ Division of Consumer Affairs. The Bergen County government website provides consumer protection contacts.
What Insurance Typically Covers on Siding
Typically Covered
- Wind damage from a documented storm event (torn, missing, or displaced panels)
- Hail damage with visible impact evidence
- Impact damage from windborne debris (falling tree limbs, roof material)
- Fallen tree damage to siding
- Secondary water damage inside the wall assembly if directly caused by storm-caused siding failure
- Damaged trim, flashing, or fascia from the same storm event
Typically NOT Covered
- Gradual fading, weathering, or color deterioration
- Damage from missed maintenance (loose panels that came apart, never re-caulked trim)
- Cosmetic hail damage on some newer policies (particularly on metal siding — check your policy)
- Matching costs when the profile is discontinued (varies by policy)
- Wall assembly damage that pre-dates the storm event
Every policy is different. Read yours or ask your agent. Bergen County siding storm claims often turn on how well the damage documentation shows storm cause versus long-term wear.
The 48-Hour Siding Checklist
- ☐ Safety check complete. No downed lines, no imminent falling siding, no active water intrusion.
- ☐ Ground-level siding inspection photographed and documented.
- ☐ Impact damage, missing panels, damaged trim all noted.
- ☐ Corners and window/door transitions checked.
- ☐ Interior water damage checked (adjacent walls, insulation, mold indicators).
- ☐ Siding profile, color, and material documented for insurance and replacement matching.
- ☐ Insurance company notified. Claim number in hand.
- ☐ Matching provisions in policy understood.
- ☐ Temporary protection in place if openings exposed to weather.
- ☐ Storm-chasers refused. Door-knockers turned away.
- ☐ Licensed local contractor contacted for permanent estimate.
- ☐ 2–3 written estimates in process.
- ☐ HIC license and insurance verified for each estimate.
- ☐ Bundled roofing/gutter/siding estimate if multiple systems damaged.
Local Bergen County Siding Storm Response
If your Bergen County home took siding storm damage — torn panels, hail impact, missing sections, damaged trim, or water intrusion in the wall assembly — Nuvista handles siding storm response across the county. We’re a licensed New Jersey general contractor with real insurance, a real Bergen-area presence, and experience running the full storm-damage claim process alongside residential roofing, gutter, and siding work. We handle siding installation and replacement, residential roofing, and gutter replacement as a bundled scope when the storm hits all three.
If you need a real inspection, a written estimate, or help thinking through the insurance claim process and matching decisions, request a free estimate — we’ll walk the property, put together a written scope, and give you the honest read on what the storm actually did.